Net Worth Tracker vs Budget App: What Each One Shows
Learn how net worth tracking and budgeting answer different questions, and choose a recordkeeping routine that fits your needs.

Alex Chen
Product Manager & Personal Finance Advocate
Net Worth Tracker vs Budget App: What Each One Shows
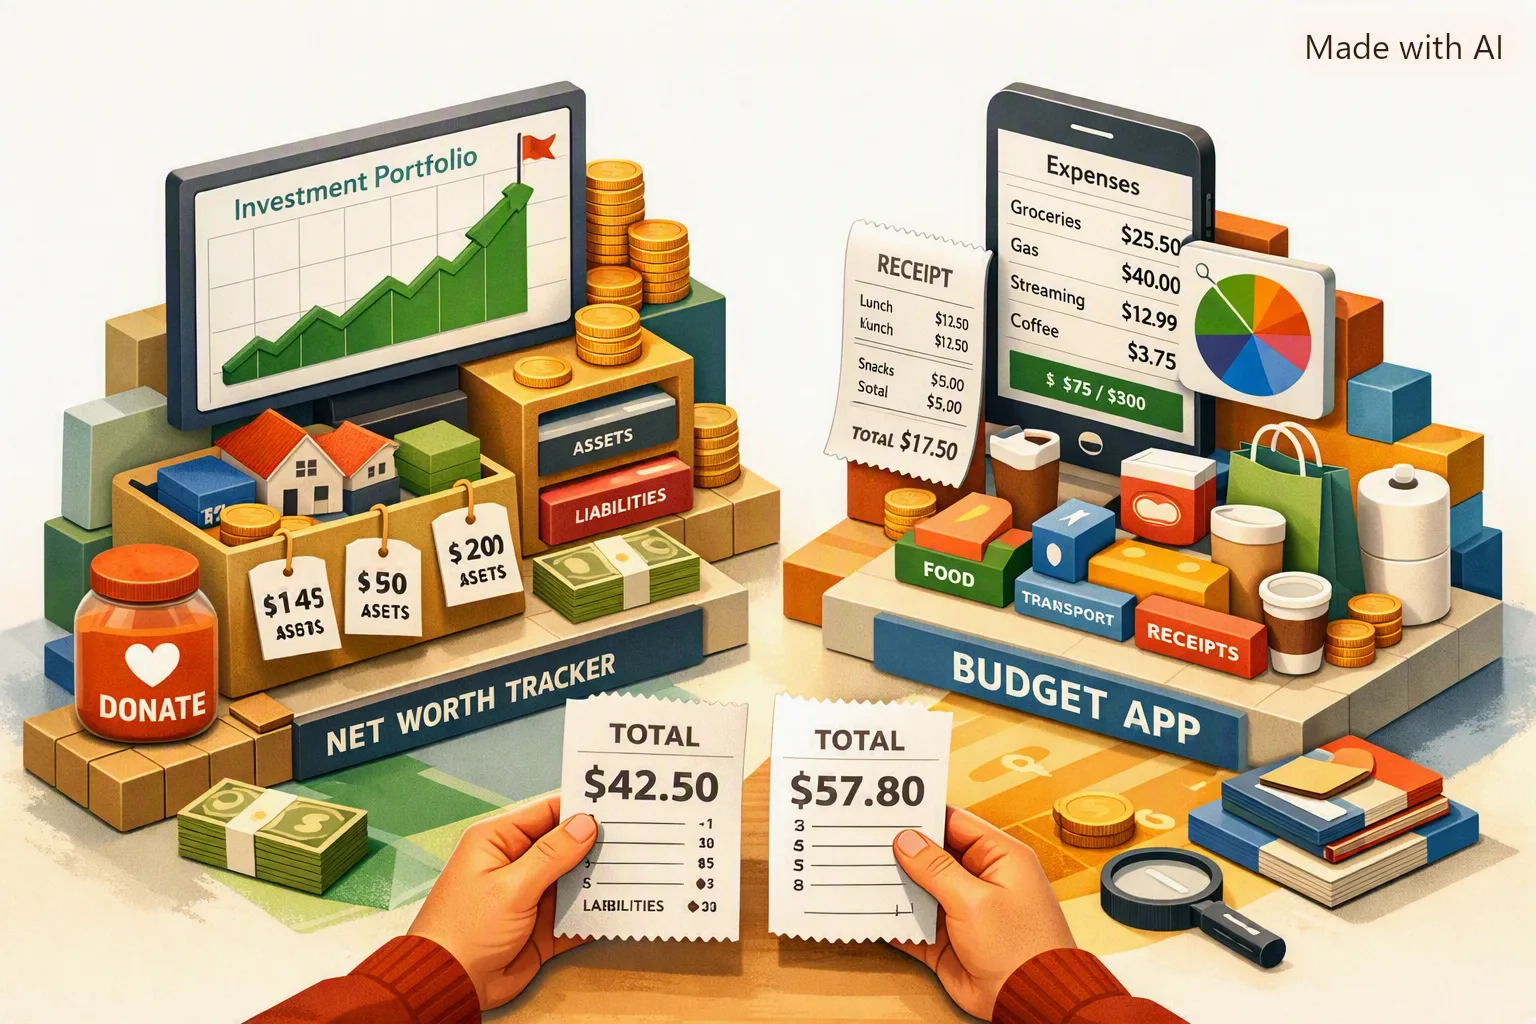
Bottom line: A net worth tracker records what you own and owe, while a budget app helps you plan or review income and spending. Use a net worth statement when you need a balance-sheet snapshot, and use a budget or spending tracker when you need to examine cash flow. The two records can work together, but neither one automatically explains the other.
The U.S. Securities and Exchange Commission’s Investor.gov guide describes a net worth statement as assets minus liabilities and recommends tracking income and expenses as a separate step. This article uses those plain definitions to compare the tools and build a practical review routine.
What each tool measures
| Tool | Main question | Typical records |
|---|---|---|
| Net worth tracker | What do I own and owe at this point in time? | Account balances, investments, property, loans, and other liabilities |
| Budget app | How do I want to use available income, or how did I spend it? | Income, bills, planned categories, transactions, and spending totals |
| Expense tracker | What purchases happened, and what did they contain? | Merchant, date, amount, category, and sometimes receipt items |
Product features differ, so check whether an app updates balances from connected accounts, asks you to enter them, or only records purchases. Do not assume that a tool covers all three jobs because it has a dashboard or chart.
What a net worth tracker can tell you
A net worth statement adds the value of assets and subtracts liabilities. Depending on your needs, the list can include checking and savings balances, investments, real estate, loans, and credit-card balances. Investor.gov recommends updating the statement periodically so you can compare it with earlier snapshots.
This view can help you see whether reported assets and debts changed over time. It does not, by itself, show which purchases caused a change in a bank balance or whether the month’s spending matched a plan. Those questions need transaction, budget, or expense records.
What a budget app can tell you
Budget apps help people plan future spending or organize past transactions. Some ask you to assign available money to categories before spending. Others collect transactions from financial accounts and group them after they happen. Some offer both approaches.
The Consumer Financial Protection Bureau’s spending assessment guide suggests reviewing income, expenses, receipts, and bills when preparing a spending plan. The useful schedule depends on your own cash flow and goals; there is no universal rule that everyone needs a weekly budget review and monthly net worth review.
A budget app may show spending totals by category, but the source data matters. A bank transaction normally identifies a merchant and total. A receipt may include item descriptions and quantities. Whether a particular app extracts and stores those receipt details is a product-specific feature to verify.
Tip
Use a cadence that fits your records and decisions. Update net worth periodically and review spending when the timing of bills, changes in income, or your goals make it useful.
Pick the tool that matches the question
Choose net worth tracking when you need a balance-sheet view
Use a net worth record when you want to list balances, assets, and debts in one place. Decide which items belong in your personal statement and use a consistent approach when you update their values. If the value is an estimate, label it so you do not confuse it with a current account balance.
Choose a budget app when you need a spending plan
Use a budgeting tool when you want to set category amounts, plan for bills, or compare actual spending with a plan. Before choosing, check how the app gets its records and whether you need to enter or correct transactions yourself.
Choose an expense tracker when you need purchase records
An expense tracker can keep a record of purchases and receipts. Yomio is receipt-first: it lets you scan or upload receipts, review purchase records, and use item details extracted from receipts. It does not import transactions from bank accounts or provide a complete net worth statement. See YNAB vs Yomio for a comparison of active budget planning and receipt-based records.
List the features you want to compare
Select requirements that matter to you. This checklist does not rank apps or verify vendor features.
Build a simple review routine
Use a schedule that matches when your records arrive and when you make decisions. The steps below are a starting point, not a recommended frequency for every household.
- Choose one question for the review. Examples include whether bills are covered, which categories changed, or whether a debt balance is moving as expected.
- Gather the source records. Use statements for account balances, bills for amounts due, and receipts when purchase details matter.
- Update the right tool. Add balances to the net worth statement and income or spending records to the budget or expense tracker.
- Check for missing or duplicate information. Compare app records with statements or receipts before drawing conclusions.
- Write down one follow-up. If something changed, note whether you need to review a bill, correct a category, or update an asset estimate.
The CFPB provides a spending tracker for recording monthly expenses by category. Investor.gov also provides a plain-language guide to listing assets and liabilities. These simple records can be kept with paper, a spreadsheet, or software that fits the task.
Common mistakes to avoid
Treating a rising net worth as proof that a budget is working. Asset values, debt, income, and spending can change for different reasons. Use the records that answer the question you are asking.
Treating a spending total as a net worth statement. A list of purchases does not show every asset or liability. Keep a separate balance record if you need that picture.
Assuming that every transaction label explains a purchase. Merchant and amount may not explain what was inside a mixed basket. Keep the receipt if item-level detail matters to you.
Changing tools before checking what will transfer. Export a small sample and confirm whether categories, notes, attachments, balances, and receipt images can move to the new product.
Keep purchase details with the receipt
Yomio helps you capture receipts and review the purchases inside them. Use a separate budget or net worth tool for the records it does not track.
Explore Receipt TrackingFrequently asked questions
Can I use a budget app and a net worth tracker together?
Yes. Use the net worth record for assets and liabilities, then use a budget app for income and spending. If more than one app stores transactions, decide which one is the primary record to reduce duplicate entries.
How often should I update net worth?
Choose a frequency that is useful for your decisions and possible with the records you have. Investor.gov suggests updating a net worth statement periodically; the exact interval is not the same for everyone.
Does receipt-level tracking replace budgeting?
No. A receipt tracker can provide details about a purchase, while a budget helps plan or review income and spending. They serve different purposes.
Does a net worth tracker show why my spending changed?
Not necessarily. It may show balances and liabilities, but understanding spending usually requires bills, transaction records, budgets, or receipts.