Year-End Business Expense Reconciliation: A Checklist Before You Close the Books
Use this checklist to reconcile business records, review mileage and contractor payments, and prepare questions for your bookkeeper or tax professional.

Alex Chen
Product Manager & Personal Finance Advocate
Year-End Business Expense Reconciliation: A Checklist Before You Close the Books
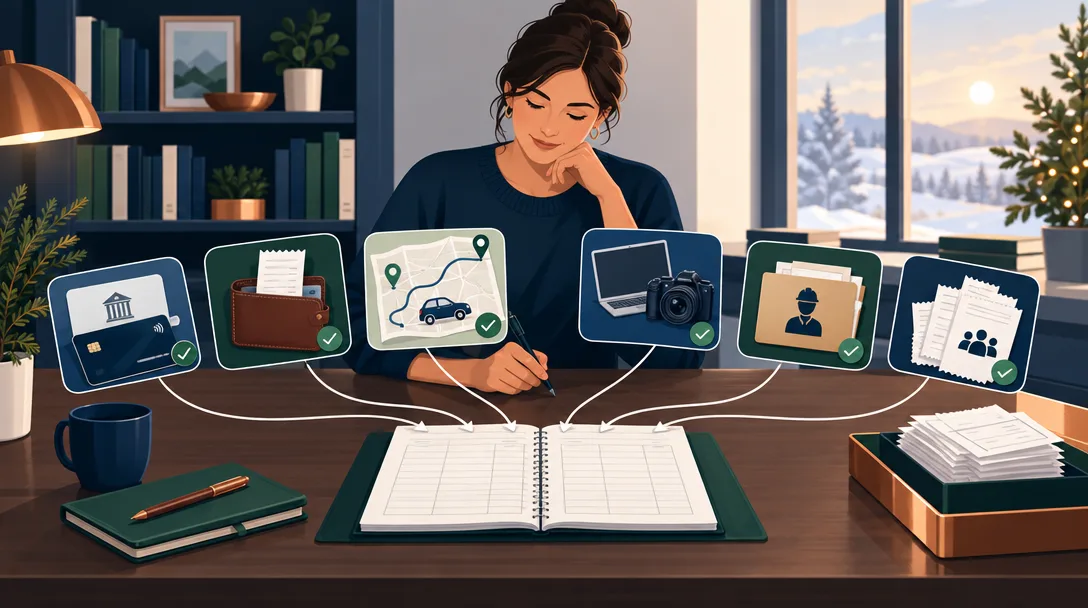
To close the books, match each business account to its statement, find business costs paid from personal accounts, review mileage records and contractor totals, then send unresolved tax questions to your preparer. This checklist covers selected U.S. federal rules for year-end 2026; it does not decide whether a cost is deductible. Yomio exports expense data as CSV for bookkeeping workflows, but it does not connect directly to QuickBooks or Xero.
Key takeaways
- Reconcile all business accounts (checking, savings, credit cards, PayPal/Stripe) against bank and card statements line-by-line before closing the year.
- Flag business expenses paid from personal accounts and ask your bookkeeper how to record them.
- Check that mileage uses the rate for the date driven: 72.5 cents per business mile from January 1 through June 30, 2026, and 76 cents from July 1 through December 31, 2026. See the IRS rate table.
- Review equipment purchases with a tax professional; Section 179 and bonus depreciation depend on property eligibility, acquisition and service dates, and vehicle limits.
- For payments made in 2026, the Form 1099-NEC threshold is $2,000 for covered payments. Check the IRS information-return guidance and recipient/payment exceptions.
Your year-end reconciliation framework
Step 1: Reconcile every account against your bank and card statements
Start with the foundation: a line-by-line match of every transaction in your books against your bank and card statements. This catches data-entry errors, duplicate transactions, and the occasional transaction that never posted.
What to pull:
- Final month bank statement for all business checking/savings accounts.
- Latest credit card statement for every business card.
- Final reconciliation report from PayPal, Stripe, Square, or other payment processors (if applicable).
What to match:
- Deposits: Compare bank deposits to revenue in your books; flag any missing or mismatched amounts.
- Expenses: Match recorded charges to the relevant statements and supporting records; investigate items that are missing, duplicated, or recorded in a different period.
- Outstanding items: Note any checks issued but not yet cleared, or reimbursements in transit.
Reconciliation helps you identify differences between your records and statements before you close the books.
Step 2: Identify expenses paid from personal accounts
Business purchases paid from personal accounts can be missed in the business records. Review owner and employee accounts for possible business transactions, then confirm the purpose and ask your bookkeeper how to record them.
Action: Walk through your personal credit card and checking statements from January 1 through December 31. Look for:
- Vendor invoices paid from your personal card (e.g., a supplier invoice charged to your Visa).
- Reimbursements for business expenses paid by team members.
- Professional services (accounting, legal, consulting) invoiced to you personally.
- Software subscriptions or tools paid via personal card.
For each personal-account transaction you identify:
- Verify it was for business (not a personal purchase incorrectly coded).
- Note the date, amount, vendor, and business purpose.
- Keep the supporting details and ask your bookkeeper how to record the transaction based on who paid and your accounting method.
- If it's an employee reimbursement, check the company policy and required support before recording payment.
This review can surface records that need follow-up; whether a cost is deductible depends on the facts and applicable tax rules.
Step 3: Finalize and verify mileage logs
If you use the standard mileage method, keep records that support the date, destination, business purpose, and miles for each business trip. Do not assume an incomplete log is automatically accepted or rejected; ask your tax professional how the available records apply to your situation.
Mileage log audit checklist:
- Keep trip details: record the date, destination, business purpose, and miles driven as required for your substantiation method. See IRS Publication 463.
- Purpose is clear enough to review: a note such as "client meeting in Boston" gives more context than "business." Apply the substantiation rules for the expense and method used.
- Check distances for reasonableness: A mapping tool can help review an existing trip record, but a route estimate does not replace required mileage substantiation.
- The rate is correct for the period driven: The IRS lists 72.5 cents per business mile from January 1 through June 30, 2026, and 76 cents from July 1 through December 31, 2026. Apply the rate that matches each trip date.
- Separate business and personal driving: Regular travel between home and a main or regular workplace is generally personal commuting under IRS guidance. Special rules can apply, including for a qualifying home office or temporary work location; review Publication 463 or ask a tax professional.
- Keep the totals your method needs: Record annual miles and business miles. The standard-mileage method and actual-expense method use different calculations, so ask a tax professional which records apply.
If your mileage records are incomplete: Gather supporting information such as calendar entries, meeting notes, or emails, and show it to your tax professional. Do not invent or backdate trip details. The IRS requires adequate substantiation, and whether available evidence is sufficient depends on the facts and applicable rules.
Step 4: Audit equipment purchases for Section 179 vs. depreciation
Section 179 may allow a business to expense eligible property, subject to dollar, business-income, and property-specific limits. For tax years beginning in 2026, the maximum general deduction is $2,560,000, phased down when qualifying property placed in service exceeds $4,090,000. Passenger vehicles have additional limits. Eligibility also depends on the property and its use, so review purchases with a tax professional before choosing an election.
For each equipment purchase in 2026:
- Is it eligible? Section 179 eligibility depends on the property, how it was acquired, when it was placed in service, and how it is used. Certain tangible property and specific improvements to nonresidential real property may qualify; land does not. Check IRS Publication 946 for the rules and exceptions.
- What is the purchase cost? Section 179 limits the total deductible amount to $2,560,000 in 2026. This limit is reduced dollar-for-dollar by the cost of Section 179 property placed in service that exceeds $4,090,000.
- Is it a sport utility vehicle (SUV)? A $32,000 Section 179 cap applies to certain heavy SUVs placed in service in 2026. The rule has vehicle definitions and exceptions; do not apply the cap to every SUV or truck without checking Publication 946.
- Could additional first-year depreciation apply? The OBBBA restored 100% additional first-year depreciation for qualified property acquired and placed in service after January 19, 2025, subject to statutory eligibility rules. Passenger vehicles have separate depreciation caps. See Rev. Proc. 2026-15 and ask a tax professional to review acquisition and service dates.
Do not assume that a vehicle's purchase price can be fully deducted or that a fixed remainder must be depreciated. Section 179 and additional depreciation interact with vehicle-specific limits, business-use percentage, eligibility, and elections.
Action: List business property and improvement purchases whose tax treatment has not been reviewed, with acquisition and placed-in-service dates. Ask your tax professional which items may qualify and whether any election fits your circumstances.
Step 5: Verify 1099-NEC contractor payments and thresholds
For covered service payments made in 2026, the IRS information-return page lists a $2,000 Form 1099-NEC threshold, compared with $600 for payments made before 2026. Exceptions apply, including rules for the payee, payment type, and backup withholding.
By February 1, 2027 (the 2026 Form 1099-NEC deadline because January 31 is a Sunday):
- Pull a list of all contractor payments (independent contractors, freelancers, consultants, vendors who issue invoices) made in 2026.
- Check the threshold and exceptions: Identify each payee with covered payments at or above $2,000, and check current IRS rules for exceptions.
- Verify contractor tax information: Obtain or confirm the contractor's Tax Identification Number (TIN), which is required on the 1099-NEC form.
- Separate 1099 contractors from employees: Payroll (W-2) employees are never issued 1099-NECs; only true independent contractors are.
Keep the payment totals and recipient information used to prepare the form. If you are unsure whether a payment is reportable, check the current instructions or ask a tax professional.
Common mistake: Combining several payees into one vendor total. Apply reporting rules to the appropriate recipient and payment type, and retain the underlying ledger detail.
Step 6: Capture and categorize all team-member receipts
If your business reimburses employees or team members for out-of-pocket business expenses, or if team members submit expenses for approval, year-end is the time to finalize all pending receipts and category assignments.
Action:
- Email all team members a deadline (e.g., December 15) to submit outstanding receipts for 2026 expenses.
- Request the information required by policy: Record the date, vendor, amount, business purpose, and category when your company policy or applicable rules call for them.
- Match receipts to bank/card statements: Verify that each receipt corresponds to an actual charge in your business accounts.
- Categorize consistently: If you use QuickBooks or Xero, ensure all team-submitted expenses use the same category taxonomy as your direct expenses, so exports are clean and accountants spend less time reclassifying.
Why this matters for team expense management: Yomio Business Mode lets team members submit receipt records for review. An administrator can configure an approval step, then export expense data as CSV for a separate bookkeeping workflow. The export does not replace statement reconciliation or tax review.
Common mistakes that derail reconciliation
1. Confusing outstanding checks with uncaptured expenses: An outstanding check (issued but not yet cleared) should be flagged as "pending" in your reconciliation, not entered as missing. When it clears in January, it will appear on your statement and resolve naturally. Recoding it as a January expense inflates next year's numbers.
2. Accepting "business travel" without a purpose: A travel expense may be deductible when it qualifies under the applicable rules and has adequate substantiation. A memo that only says "trip" or "travel" may not explain its business purpose. See IRS Publication 463.
3. Recording an employee reimbursement twice: A reimbursement involves the underlying expense and a payment to the employee. The correct entries depend on how the expense and payable were first recorded; ask your bookkeeper to reconcile both records without counting the cost twice.
4. Delaying contractor payment documentation: Waiting until the filing deadline to confirm payment totals or recipient details can create avoidable errors. Request tax information early, then follow the current IRS filing and furnishing deadlines for the form.
Close the year with a clean, categorized expense trail
Yomio Business Mode helps teams collect receipt records, review submitted expenses, and export expense data as CSV for bookkeeping workflows. It does not connect directly to QuickBooks or Xero or determine tax treatment.
See Business Mode